Why Your Money Mindset Keeps Repeating Patterns
The purchase that leaves you with a familiar pang of regret is rarely just about the purchase. The account balance you avoid checking, the raise you struggle to ask for, or the savings goal that keeps disappearing all point to something deeper: a pattern. Your money mindset is the set of beliefs, emotions, expectations, and protective habits that shape what money means to you and what you do when it enters, or leaves, your life.
That does not mean financial challenges are all in your head. Income, debt, family obligations, health, discrimination, and economic conditions are real forces with real consequences. But two people can face a similar financial decision and respond in dramatically different ways. The difference often lies in the story each person has learned to tell about money.
When you can recognize that story, you gain a choice. You can stop treating every repeated behavior as a character flaw and start seeing it as information.
What a Money Mindset Really Reveals
A money mindset is not simply whether you think positively about wealth. Forced optimism is no more useful than constant worry. A healthier mindset is accurate, self-aware, and flexible. It lets you acknowledge a difficult number without turning it into a verdict about your worth. It helps you enjoy money without using it as your only source of comfort, status, or safety.
Most money beliefs begin before we have language for them. Perhaps you watched a parent work constantly but remain financially stressed. Maybe money was scarce, unpredictable, fought over, or never discussed. Maybe it was used as proof of success, a source of control, or a way to show love. Those early experiences can become quiet rules: “I have to work twice as hard to deserve more.” “Money never stays.” “If I have enough, someone will need something from me.” “People like me do not invest.”
The rule may have made sense at one point. It may even have helped you adapt to your environment. The problem is that an old rule can keep directing an adult life long after it has stopped serving you.
This is why generic advice can feel strangely ineffective. Telling an anxious saver to “just invest” may ignore the fear beneath the hesitation. Telling an emotional spender to cut discretionary expenses may create a few disciplined weeks, then trigger a rebound. The behavior is visible. The emotional job the behavior performs is not.
Your Financial Archetype Is a Clue, Not a Label
One useful way to make patterns visible is through financial archetypes. An archetype is not a box you must stay inside. It is a lens for recognizing the instinctive role you tend to play around money, especially under pressure.
One person may be a vigilant protector, always preparing for what could go wrong. Their strength is foresight; their blind spot may be denying themselves present-day enjoyment or delaying decisions until certainty arrives. Another may be a generous provider, quick to support friends and family. Their care is real, but they may confuse boundaries with selfishness and repeatedly put their own stability last.
Someone else may be driven by achievement, tying financial progress to identity and external proof. That motivation can build a powerful career, while also making rest, contentment, or a temporary setback feel intolerable. A freedom-seeker may resist budgets because structure feels like confinement, even when a simple system would create more choices later.
None of these patterns are inherently bad. Every archetype carries an intelligence, a need, and a risk. The goal is not to eliminate your natural tendencies. It is to understand when they are helping you make a conscious choice and when they are quietly making the choice for you.
Ask yourself a more useful question than “Why am I bad with money?” Try: “What is this behavior trying to protect, prove, avoid, or create?” The answer often changes the next step.
How Money Mindset Shows Up in Everyday Decisions
Mindset is most visible in moments that seem small. You receive a bonus and immediately spend it because holding extra cash feels unfamiliar. You leave a bill unopened because seeing the number makes the situation feel more real. You keep undercharging for your work because asking for more brings up fears of rejection. You research investments for months but never begin because making an imperfect choice feels unsafe.
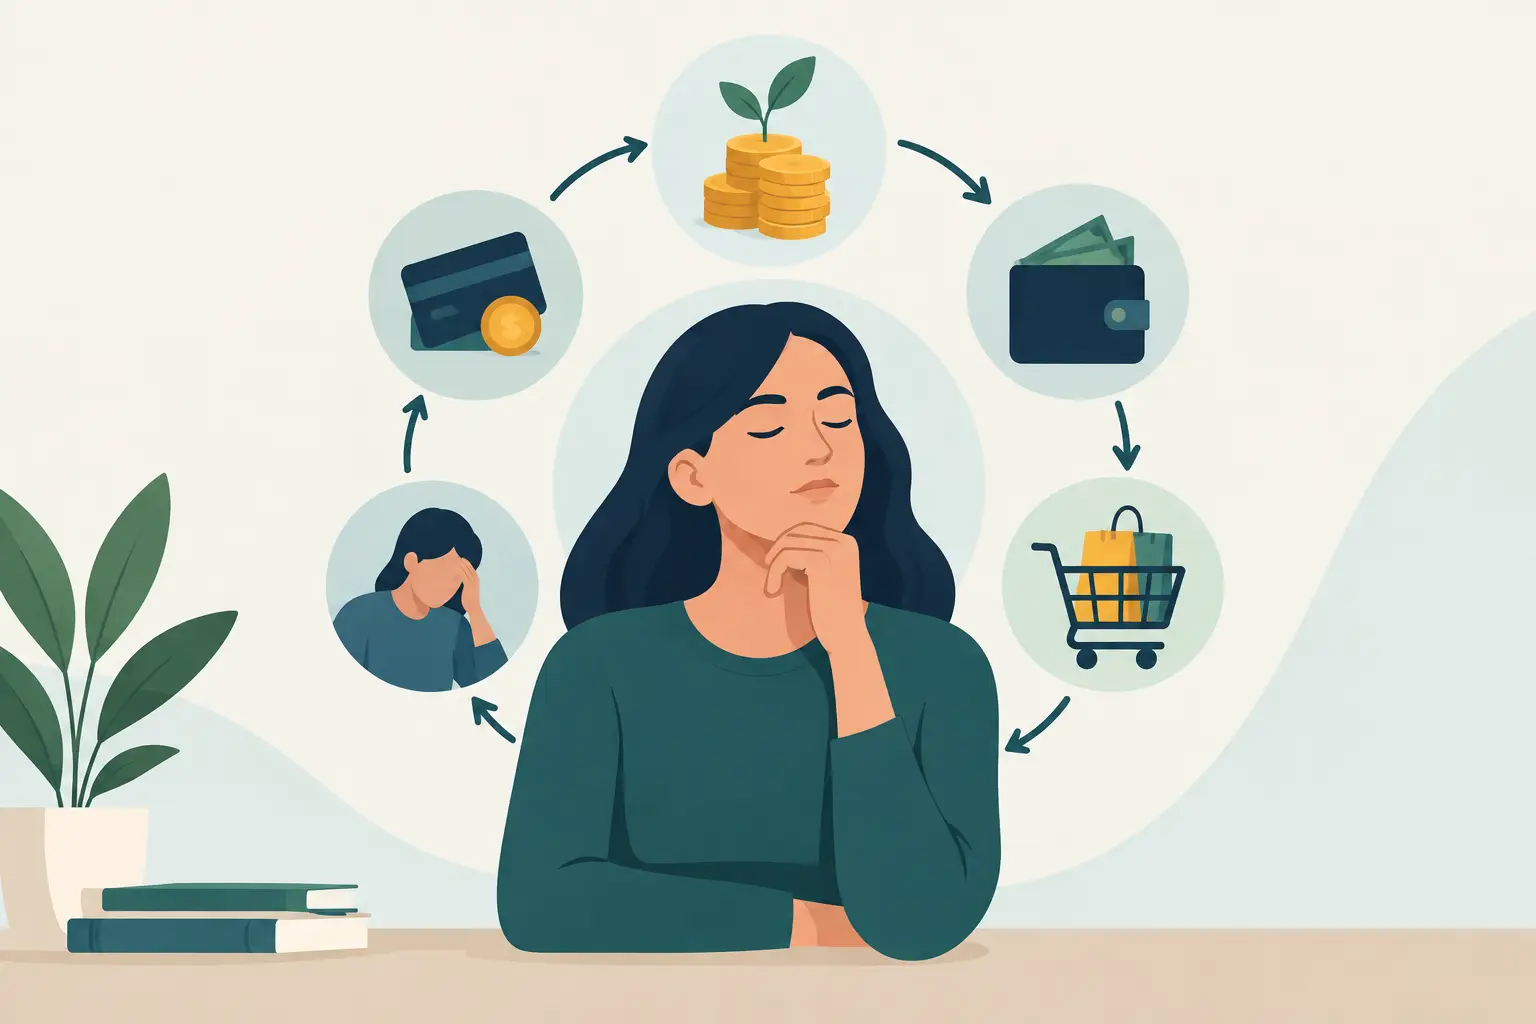
These are not identical problems, so they should not receive identical solutions. Still, they often follow a common cycle:
- A trigger appears, such as stress, uncertainty, a social comparison, or unexpected money.
- An emotional interpretation follows: “I need relief,” “I will never catch up,” or “I have to prove I am doing well.”
- A familiar behavior delivers short-term comfort, control, or escape.
- The financial consequence creates more stress, reinforcing the original belief.
The cycle can make change feel personal and permanent: “This is just who I am.” But a repeated pattern is learned, and learned patterns can be revised. Not overnight, and not through shame. They change through awareness, different conditions, and enough repetition for a new response to become believable.
How to Shift a Money Mindset Without Pretending
Start by observing before you try to correct. For two weeks, notice the moments when money feels emotionally charged. Record what happened, what you felt, what you told yourself, and what you did next. Keep it brief. The point is not to create another performance standard. It is to collect evidence.
Then look for the sentence beneath the behavior. If you overspend after hard days, the sentence may be, “This is the only way I get to feel cared for.” If you hoard every extra dollar, it may be, “If I relax, something bad will happen.” If you avoid negotiating, it may be, “Wanting more will make people judge me.” A belief becomes easier to change when you can name it precisely.
Next, build a response that respects the need without repeating the cost. Someone who spends for relief may create a small, planned comfort allowance and add another soothing ritual that does not require a purchase. Someone who fears investing may begin with education and a modest automatic contribution rather than waiting for perfect confidence. Someone who gives beyond their means may decide in advance what support they can offer without destabilizing themselves.
This is where behavior change becomes personal. The right action is not always the most aggressive one. A large savings target may motivate one person and paralyze another. Detailed tracking can be grounding for a numbers-oriented person but consuming for someone prone to anxiety. The best system is the one that creates enough structure to support you without turning money into a daily threat.
Build Evidence for a Different Financial Story
New beliefs become credible when your actions give them proof. Instead of telling yourself, “I am great with money now,” choose a statement you can test: “I can look at my accounts even when I feel nervous.” Then practice that skill on a regular schedule. “I can keep some money for future me and still enjoy my life.” Put a modest amount aside after each paycheck and use a planned amount guilt-free.
Small wins matter because they challenge the old story with lived evidence. You do not need to solve every financial goal at once. You need to become someone who can stay present with money decisions, recover from mistakes, and make the next choice with more awareness than the last.
It can also help to separate identity from circumstance. A credit card balance is a balance, not a moral score. A high salary does not automatically mean security. A missed savings month does not erase your progress. When you stop using numbers as evidence of your value, you can finally use them for what they are: useful information.
The Money Story approach begins with that distinction. Understanding your financial archetype can reveal why certain advice has not stuck, and what kind of practice may actually fit the person you are. Clarity is not a substitute for action, but it makes action far more targeted.
The next time a money decision brings up urgency, guilt, or fear, pause long enough to ask whose rule you are following. You may find that the story is old. And if it is old, you are allowed to write the next line differently.